Money in a traditional IRA or 401(k) has not been taxed yet. It is taxed when it comes out, at whatever rate applies that year. Nobody knows that rate today, and the federal government’s growing interest bill is one reason to take the uncertainty seriously. That uncertainty has a name: tax-rate risk.
Here is why it came up this month. The Treasury reported on September 11 that the federal government has spent more on interest so far this fiscal year than on Medicare. The national debt passed $40 trillion the day before. Inflation is holding at 3.4 percent.
None of that is a prediction about your taxes. It is context for a question most people with a pre-tax account have not asked: what rate is this money going to be taxed at, and who decides?
If you already know you want to talk this through, you can
schedule a conversation →
Tax-rate risk is the exposure of money in a pre-tax account to a tax rate, and a set of rules around it, that have not been settled yet. The rate is one term. The others are:
Congress has changed each of them within living memory.
When you put money into a traditional IRA or 401(k), you took a deduction. In exchange, the government deferred its share until you take the money out. The rate it applies is the rate in effect in the year you withdraw, not the rate in effect when you contributed.
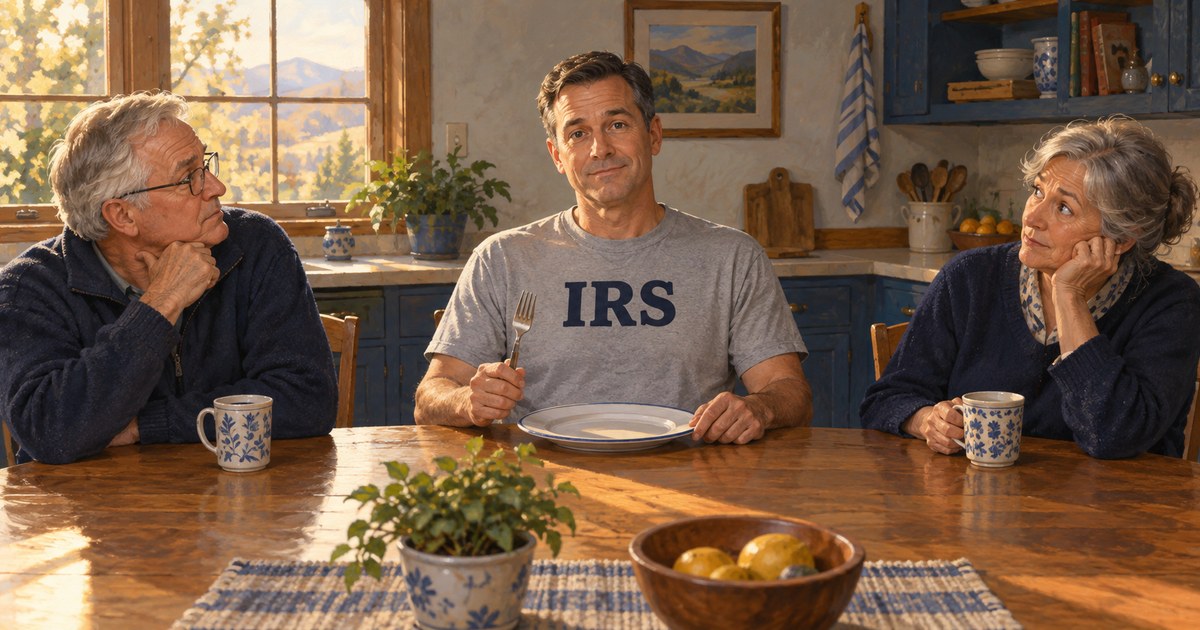
Picture the kitchen table after the kids have moved out. It is finally quiet, except for one more chair. The IRS is still living in your pre-tax account, and it still needs to be fed every year, for the rest of your retirement. What nobody has told you is how big its appetite is going to be. That gets decided later, by people you have never met.
For most households, that account holds most of what they have set aside. So the size of that appetite is the largest number in their retirement that nobody has settled.
A government spending more than it collects has three tools:
I won’t predict which mix. There are serious people who argue that higher taxes, if they come, are more likely to arrive as tightened deductions, phaseouts, surtaxes, or expanded taxation of benefits than as a headline bracket increase. There are also reasonable arguments that rates stay where they are. Both camps agree on one thing: the terms on your pre-tax money are not settled, and the tax rules that will apply to future distributions cannot be known with certainty today.
The terms have moved before.
1983 / 1993. Social Security benefits were not taxable until 1983, when up to half became taxable above an income threshold. In 1993 that rose to 85 percent. The thresholds have never been adjusted for inflation.
2019. The SECURE Act required most non-spouse heirs to empty an inherited pre-tax IRA within ten years instead of over their lifetime, compressing decades of deferred tax into a decade.
Neither change touched a bracket. Both changed what the government collects from pre-tax money.
The cost is not abstract, and it does not wait for a policy change.
At the applicable RMD age under current law, required minimum distributions force money out of a pre-tax account whether you need it that year or not. Each distribution is taxed as ordinary income at that year’s rate. And because the same income figure drives other calculations, a larger distribution can also:
So a household with most of its retirement money in a pre-tax account is not carrying one unknown. It is carrying one unknown that feeds three other calculations, every year, for the rest of retirement.
That is the risk. It is yours to absorb unless you move it.
If you have never looked at how much of your retirement money is sitting in the unsettled column, that is where we start. No obligation, no pitch, and you leave with your own numbers.
A fixed indexed annuity with a lifetime income rider transfers a different risk, the risk of outliving your money, to an insurance company built to carry it. Premiums go in, an income base grows during a waiting period, and when you turn income on, the company contracts to pay it for life. That part works the same in both paths below. What changes is the tax.
Path one
Roll the traditional IRA into the contract. No tax at rollover. The account stays pre-tax. When lifetime income starts, each payment is taxed as ordinary income at that year’s rate, and RMDs still apply. The company has taken the longevity risk. The tax-rate risk stays with you.
Path two
Convert to a Roth IRA and fund the contract there. You pay income tax on the converted amount in the year you convert, at a rate you know. The contract is issued as a Roth IRA. Lifetime income from it is not taxed under current tax law, as long as you are at least 59½ and the Roth has been open at least five years. There are no RMDs during your lifetime. The company has taken the longevity risk, and under current tax law, the tax question is settled.
It is the same product with the same income mechanics.
The one decision is whether to settle the tax now, under today’s rules, or find out later.
Path two is not right for everyone. If your income in retirement drops enough that your tax bracket falls below today’s, converting means paying more tax than you had to, even in a higher-tax world. The deficit sets the conditions, but your own numbers decide the case: what you would pay to convert now, and what you would likely pay later if you don’t. That comparison is where we start, and when a conversion is large enough to need a tax professional at the table, we bring one in.
Guarantees are backed by the claims-paying ability of the issuing insurance company. Rider terms, costs, and restrictions vary by contract. The income benefit base is used to calculate lifetime income; it is not the contract’s cash value and is not available for lump-sum withdrawal.
The question this post is really about is not whether taxes go up. It is how much of your retirement income you want decided, and how much you are comfortable leaving open.
Money in a pre-tax account is unsettled. The amount is known; the after-tax amount is not.
Money that has been through a Roth conversion is settled under current tax law. You paid the price, you know what you kept, and the uncertainty about the future rate on that money has been reduced rather than left open.
There is no rule that says everything has to move to one column. Most households end up with some of each, on purpose. But the split should be a decision, not a default. Right now, for most people, it is a default.
Is my 401(k) taxed at today’s rate or a future rate?
It is taxed at a future rate. Traditional 401(k) and IRA withdrawals are taxed as ordinary income in the year you take them, at whatever rate applies that year. The deduction you received when contributing was based on the rate then; the tax you pay is based on the rate later.
Does the national debt affect my retirement taxes?
It affects them indirectly. A government facing rising interest costs has to borrow more, spend less, or collect more, and pre-tax retirement accounts are one of the largest pools of not-yet-taxed money in the country. No one can say how or when that pressure shows up in tax law. The point is that the rate on your pre-tax money is not fixed.
Can I move an IRA into a lifetime income annuity without paying tax now?
Yes. A direct rollover from a traditional IRA or 401(k) into an annuity issued as a traditional IRA is not a taxable event. Income from it later is taxed as ordinary income. Converting to a Roth IRA instead is taxable in the year of conversion.
Is income from an annuity inside a Roth IRA taxable?
It is not taxable under current tax law, provided the distribution is qualified: you are at least 59½ and the Roth IRA has been open at least five years. The five-year clock starts with your first Roth contribution or conversion, not with the annuity.
This is tax information, not tax advice. Rules change, and individual situations differ. We involve a tax professional when your situation calls for one.
You do not need to decide today whether to convert anything. You need to know what your split looks like now, and what the settled column would cost you at today’s rates versus what the unsettled column might cost you later. That is a 30-minute conversation with your actual numbers on the table.
Ready to see where your retirement money actually stands? We walk through your numbers together. It takes about 30 minutes, costs nothing, and you leave knowing how much of your income is settled and how much is still open.
Sources: Social Security Amendments of 1983 (P.L. 98-21); Omnibus Budget Reconciliation Act of 1993 (P.L. 103-66); Setting Every Community Up for Retirement Enhancement Act of 2019 (P.L. 116-94). U.S. Department of the Treasury, Monthly Treasury Statement, August 2026 (released September 11, 2026). U.S. Treasury, Debt to the Penny, September 10, 2026. U.S. Treasury, Daily Treasury Par Yield Curve Rates, September 11, 2026 (30-year: 5.36 percent). U.S. Bureau of Labor Statistics, Consumer Price Index, August 2026. IRS Publication 590-B (2025), Distributions from Individual Retirement Arrangements.
Mark Rudder, Licensed Insurance Producer in Arizona · AZ #22110541
Michelle (Lanying) Li, Licensed Insurance Producer in Arizona · AZ #21573356
and Licensed Insurance Producer in California · CA #4390834